European hotel owners are asking for more than rent
Institutional capital keeps flowing into European hospitality. What has changed is what owners expect from the structure that sits between them and the hotel.
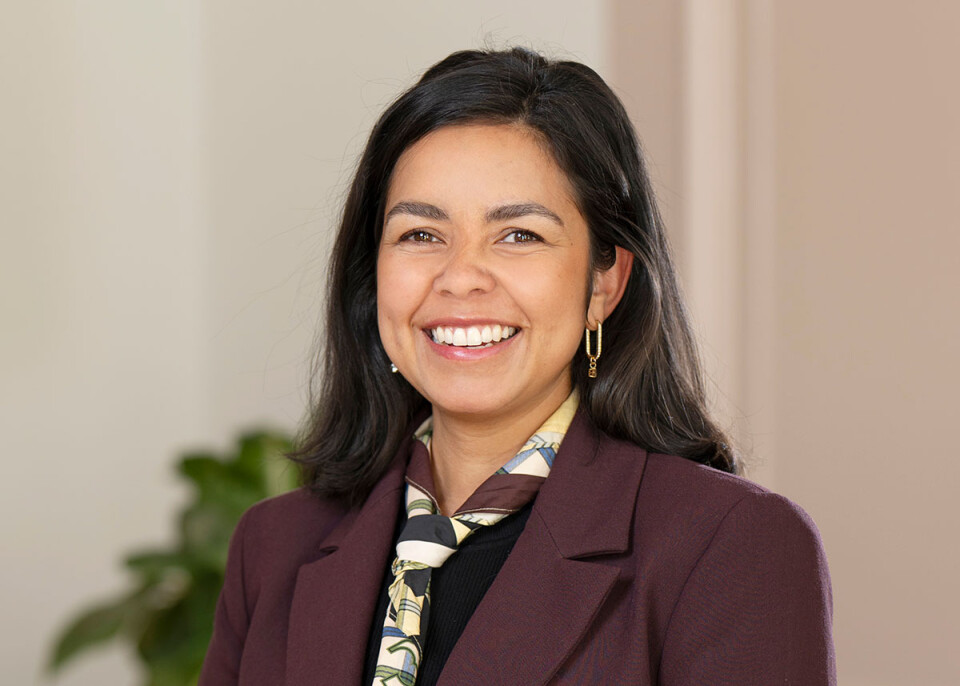
Hilda K. R. Weit is director of development (DACH) at Odyssey Hotel Group.
Institutional investors have not lost their appetite for hotels. The sector remains one of the few in European real estate with structural growth behind it and room rates give owners a natural hedge against inflation.
What has shifted is the structure they want. A fixed rent cheque, once the whole point of a hotel investment, now looks like a thin return on an asset that produces considerably more than that.
Leasing directly to a hotel brand buys predictability at a price most owners now question. The owner receives a rent payment and sees little of what generated it. The operating result stays with the brand.
Brand and operation arrive as one package, so repositioning an asset usually means reopening the entire contract. That trade worked while operating costs behaved predictably. Labour, energy and maintenance have since taught owners otherwise.
Integrated operating platforms have gained ground here. Under a management agreement with a white-label operator, the operating result stays with the owner, less an agreed management fee. So does the decision about which brand suits the asset.
A platform holding relationships across several international brand groups can flag one property midscale and another lifestyle or luxury, while the owner keeps the same operating partner throughout. One reporting line, one governance structure and the full brand landscape to choose from.
Digitisation made this workable at institutional scale. A management agreement hands operational risk back to the owner and owners of that size will not take on risk they cannot see.
Digitally enabled platforms now deliver occupancy, energy consumption, maintenance status and inspection records as live data, available on the day it happens.
An asset manager can intervene while intervention still costs little or nothing. Transparency of that quality is what makes a management agreement a governable structure rather than an act of trust.
The market has tested the proposition. A high-profile insolvency of a white-label operator prompted some investors to ask whether third-party platforms carry too much risk, and a few began weighing a return to direct brand leases.
The failures point elsewhere. Operators come undone when they grow faster than they can integrate, when they take on rigid obligations they cannot service or when they leave owners without sight of the numbers. Those are execution failures.
The dividing line sits on the balance sheet. An operator backed by a parent company willing to stand behind its obligations can absorb a weak year without passing the problem to the owner. One without that backing cannot, whatever the contract says. Owners now ask for that evidence early in negotiations, alongside reporting standards and governance.
None of this retires the lease. It turns the choice of structure into a real decision. Some owners want fixed income and accept a lower ceiling to secure it. Others want the upside and carry the operational risk to reach it.
Many want something in between, which explains why revenue shares, NOI participations and hybrid structures keep gaining ground. The operators worth working with offer the full range and say plainly which structure suits a given asset and a given owner. An operator who only sells one model is selling their own preference.
The same range applies to the work itself. Owners increasingly need a partner who can take over a running hotel mid-contract, keep the team in place, hold the operation steady and start repositioning at the same time. That work sits well outside a standard brand lease and it is where an experienced platform earns its position.
Where does this leave the European market? Capital will keep arriving and the stock of assets needing repositioning or conversion will keep growing as offices come out of use. Returns will not spread evenly. They will reach the owners who settled the question of their operating partner before closing, not after.
Rent tells an owner what a hotel pays. The right operating structure tells them what it is worth.
Subscribe now and stay informed
Joining the CRE Media Europe mailing list is quick and simple. Just provide your contact details below to be added to our distribution list and start receiving the latest news, magazines and special updates, all free of charge.
Commercial real estate (CRE) Media Europe is a free to access news and information service providing dependable, independent journalism. Our mission is to provide the pan-European real estate market with the latest trends and data points, and provide key analytical coverage to help you make better decisions in your business.
To discuss advertising and commercial partnership opportunities please contact eddie@cremediaeurope.com