Back for the next cycle
Jorge Duarte left Barings in search of a new challenge just as European real estate was approaching one of its biggest corrections in decades. Now he is back – and convinced a new property cycle has begun. He explains why Barings is backing beds and sheds, why residential beats offices nine times out of 10, why Germany is interesting again and how Barings plans to scale its European business.
This article was published in our October 2026 magazine
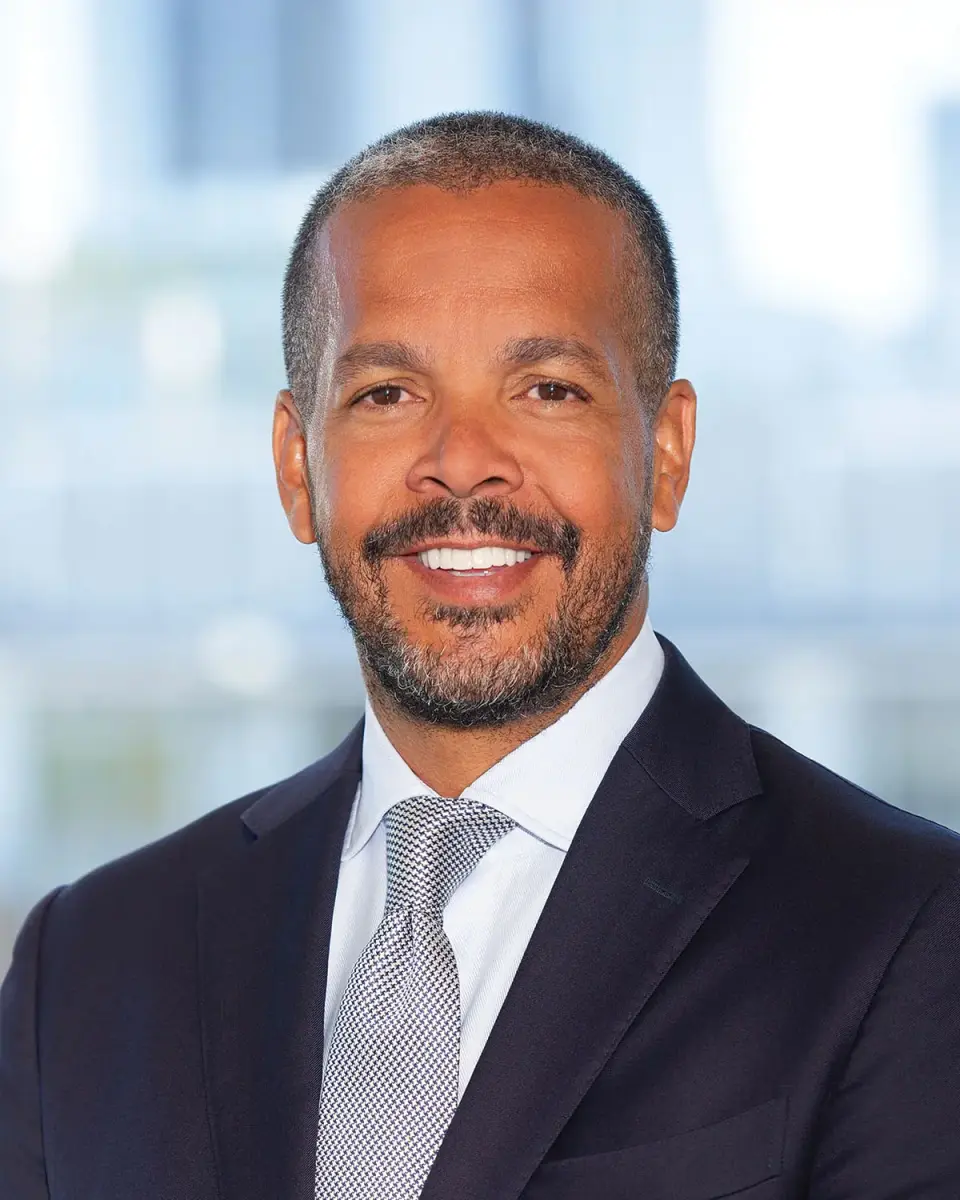
Jorge Duarte
Jorge Duarte has a refreshingly succinct explanation for why he left Barings at the end of 2021: “Impatience, probably.”
Duarte had joined the business, then Cornerstone, in 2015 and the following year launched its European core open-ended fund. By the time he departed, the fund had grown to around €3bn. But after almost seven years, the opportunity to build something new proved irresistible.
“I was looking for a new challenge,” he says. “The core fund was a great fund with a great platform, but it was a great opportunity to go and do something different at Hines with a great team and I took that opportunity.”
He joined Hines and established its European core-plus platform in May 2022. As exercises in market timing go, Duarte concedes, it was less than ideal. “In terms of timing, it wasn’t great,” he says.
Within months, the European property market was being battered by rapidly rising interest rates, debt costs were soaring and investment volumes were falling. The long period of ultra-cheap money that had underpinned property pricing was emphatically over. Yet Hines still managed to raise a couple of billion euros and invest the fund, Duarte says.
Then Nick Pink, Barings’ head of European real estate, came calling. The result was Duarte’s return to Barings in January this year as head of portfolio management, European real estate equity. This time his brief is broader. Rather than running a specific fund, he has responsibility across the fund management business.
“But there isn’t and that’s understandable. We know the concerns that investors have around interest rates and we know the geopolitical uncertainty that is out there. But we do see this as the start of a new cycle. There is still a significant spread between the risk-free rate and prime real estate, even with some of the volatility that we’ve seen in the bond markets.”
The absence of a conventional bounce in transaction volumes does not, in Duarte’s view, mean the underlying property story is weak. Indeed, one of the striking features of this correction has been the resilience of rents despite mediocre economic growth. “We continue to have pretty strong rental growth, despite constrained GDP or weak GDP growth in most European countries,” he says.
“And that is because there’s very little development happening. There’s very little modern stock coming to the market. That has been quite supportive of most sectors, even in the retail sector, which isn’t typically one of our favourite sectors.”
Duarte believes the round trip itself says something important about his relationship with Barings. “I always say to investors when we’re talking to them, I think me coming back is a double endorsement,” he says. “One, that I’m willing to come back to a company that I know very well, but also that the company is willing to take me back as well.”
More important is what he has come back to do. Duarte believes European property is finally at the beginning of a new investment cycle. Barings is in what he calls “growth mode” and intends to scale its existing European strategies significantly. Yet this is an unusual recovery. Four years after property values began correcting in 2022, transaction volumes and investor confidence remain well below what might normally be expected at this stage.
Investors could perhaps be forgiven for treating declarations of a new property cycle with caution. The market has experienced several apparent turning points since the correction began, only for geopolitical events, stubborn inflation, interest-rate expectations or bond-market volatility to interrupt the recovery.
Duarte is under no illusion that those risks have disappeared. What strikes him is how slowly liquidity has returned compared with previous cycles. “If you think about where we are post-2022, when the correction started, and we’re now four years into it, you probably think normally there would be a lot more liquidity, a lot more activity in the market,” he says.
New development has become difficult to make viable across much of Europe. Construction costs remain elevated, financing is harder to secure and planning – particularly for the centrally located assets Barings favours – can be painfully slow.
For an investor with capital to deploy, that shortage creates two attractions. Existing good-quality space benefits from constrained supply and rental growth; and in many cases buildings can now be acquired for less than it would cost to recreate them. “You are generally investing below replacement cost, which is a great basis to be investing in the market,” Duarte says.
It is one of the central ideas underpinning Barings’ strategy for the new cycle. At sector level, Barings’ highest-conviction calls will surprise few property investors. Duarte describes its preferred sectors with the familiar shorthand of “beds and sheds”. But within those broad categories, the strategy is more nuanced.
On the living side, Barings is pursuing build-to-rent, purpose-built student accommodation and affordable housing, among other residential strategies. In logistics it will invest in everything from large distribution facilities to urban multi-let industrial estates.
What ties much of the strategy together is demographics. Barings concentrates heavily on Western Europe, where it has teams on the ground, and Duarte says its starting point when selecting cities is evidence of long-term demographic demand.
“We really prioritise cities and hubs with very strong demographic tailwinds,” he says. “You can look at total population, you can look at household formation and then, depending on which sector you’re investing in, you look at the relevant age cohort.
“There are obviously risks around immigration and the political issues that come with that, but generally net immigration has been positive for demographic growth. We want to be investing in places where those long-term structural drivers are supportive.”
With institutional capital across Europe increasingly concentrated on living and logistics, there is an obvious danger. If everyone likes beds and sheds, does the weight of money eventually undermine the returns that made them attractive? Duarte acknowledges the possibility but believes it is a problem for another day.
“There’s always a danger of getting overheated,” he says. “I think we are at the beginning of a cycle, and we don’t feel that that danger is there today. Far from it. We think that pricing is very attractive in both those sectors. I’m not saying that in five years’ time that doesn’t change, and you need to continue to look at pricing and at the fundamentals, but for now we see these as a great opportunity to be buying into these sectors.”
That qualification matters. Beds and sheds is not intended as an indefinite sector bet irrespective of price. For Barings, the attraction today is the combination of structural demand and a market correction that has made the prospective returns more compelling.
Perhaps the clearest indication of how the investment landscape has changed comes when Duarte is asked about offices. The sector, he insists, was never un-investable for Barings, even at the height of post-pandemic uncertainty.
“Offices were never un-investable for us, even with the challenges that we had post-Covid,” he says. “I think the return-to-office momentum has stabilised and there is still very strong demand for high-quality, well-located, ESG-compliant stock. Offices might have fallen a little bit out of favour in the US, but in Europe we still see offices as an investable asset class.”
The problem for offices is partly relative rather than absolute. Barings has liked residential for years, but before the repricing that began in 2022, Duarte says, it was difficult to generate meaningful returns from build-to-rent, particularly for lower-risk strategies. The correction transformed the equation. “The biggest challenge for offices is that residential has become very investable,” he says. “Before 2022, residential was very expensive. It was very hard to achieve meaningful returns, even in the core space.
“Since 2022, because of the correction, residential has become much more attractive. If we’re looking at two different opportunities, and we have an office asset and a build-to-rent asset – let’s call it in the value-add space – and both are delivering similar returns, I would go for the residential nine out of 10 because there’s less risk, there’s more liquidity on exit. That, for me, is the biggest challenge for offices.”
It is a telling assessment. Offices have not ceased to be investable; rather, they have lost the privileged position they once enjoyed in institutional portfolios. They now compete for capital with a much broader range of property types that can offer comparable returns and sometimes lower risk.
The same selectivity applies within sectors. Location remains fundamental. “Location is always the first factor for us,” Duarte says. “After you look at macroeconomics and the long-term structural drivers like demographics, location is going to be key, and that applies to every single sector that we invest in.”
A similar calculation governs Barings’ approach to retail. Again, Duarte rejects the idea that retail as a whole is un-investable. But the firm is highly selective about the parts of the sector it wants to own. “We are not investing in high-street retail or shopping centres,” he says. “We’ve generally been focused on grocery and then, at the complete opposite end, luxury retail.”
The rationale is different in each case but comes down to resilience. Consumers need to buy groceries irrespective of economic conditions, while luxury retail has proved comparatively resilient to online penetration. Speaking from Paris, Duarte happens to be looking towards one of the luxury shops in which Barings has invested.
The strategy illustrates a wider refusal to treat traditional sector labels as investment theses in themselves. ‘Office’ or ‘retail’ is not enough. Barings wants the right part of a sector, in the right city, with the right supply-demand dynamics.
The firm is also prepared to move further into alternative property types when it identifies a sufficiently compelling opportunity. Self-storage is one example. Barings has been investing in the sector in Germany, although Duarte says the strategy is deliberately narrower than its pan-European approach to living and logistics.
The contrast between Spain and Germany perhaps best illustrates how Barings is thinking geographically. Spain is the easier story. “Spain has been one of the darlings of European real estate for a number of years,” Duarte says.
“It’s had the strongest GDP growth and that has been reflected in quite a lot of interest from investors in the market across different sectors. We’ve been investing in Spain for a number of years and hopefully we’re going to reap the benefits of having invested there.”
Germany offers almost the opposite proposition. Its economy has struggled, political uncertainty has weighed on sentiment and its property market has endured significant repricing. Germany has, Duarte says, been lagging behind much of the European recovery.
That is precisely why Barings is interested. “Germany is quite interesting because of some of the challenges that they’ve had,” he says. “You’ve had weak GDP, you’ve had political uncertainty and the market has repriced. We’re seeing some really interesting opportunities in Germany today because of the challenges that you see there.”
The distinction between Germany and Spain says something important about Barings’ approach. Its focus on structural fundamentals does not simply translate into buying whichever country currently has the best economic figures.
Spain appeals because its fundamentals are strong and Barings already has investments positioned to benefit. Germany appeals because weakness, uncertainty and repricing can produce opportunities that did not previously exist at acceptable returns.
If buying below replacement cost is one advantage of the current market, development might appear to offer another. A shortage of modern buildings combined with rental growth would normally provide the ingredients for new construction.
But Duarte does not think the numbers yet justify taking conventional development risk in many cases. “There are points in the cycle where it makes sense to do development,” he says. “Right now, we don’t think that’s one of those cases.”
That does not mean Barings wants no exposure to newly developed property. Instead, Duarte sees an opportunity created by developers that own attractive sites and have projects ready to proceed but lack sufficient balance-sheet capacity to deliver them. “I think there are a lot of developers with really interesting land, with projects ready to go, that because of challenges to their own balance sheets need capital to get those developments going,” he says.
“That gives us an opportunity to get very attractive pricing without necessarily taking the typical development risk. You can have the planning in place, you can have a fixed construction contract in place and then you are funding the development. So we don’t see the need to take development risk ourselves and go through the planning process, potentially with delays and everything else.”
It is an important distinction. Barings is not ruling out development forever; Duarte believes there are stages of the cycle when taking full development risk makes sense. He simply does not think this is one of them. And he does not expect the viability problem to disappear quickly.
“Planning is still one of the biggest challenges in Europe, particularly in the areas where we want to be investing, which are generally more central locations,” he says. “Construction costs are still very elevated and we don’t expect them to come down significantly anytime soon. Financing is difficult as well. Eventually, rents and rental growth are going to make those developments viable, but it’s going to take time.”
Barings intends to use the new cycle to grow, but growth does not mean trying to do everything. The European core fund is an obvious priority. The firm is also looking to grow its value-add fund series, now on its third fund, and could launch a small number of additional strategies where the market correction has created opportunities.
“We want to grow the core fund significantly,” Duarte says. “We raised a lot of capital last year, which was one of our best fundraising years, and hopefully we’re going to have another good year this year. We are also stabilising the value fund series. We’re now on Fund Three and we want to scale that over the next couple of years. And we might launch a couple of different products, but they need to be non-competing products. We don’t want to have lots of different strategies competing for the same deals.”
The emphasis is therefore on scaling what Barings already does rather than creating a sprawling European operation. “The platform that we have is pretty mature,” he says. “We’re not looking to grow much in terms of offices in Europe or number of people, but we see this as a great opportunity to scale the products that we already have.”
Does artificial intelligence make that possible? Duarte is cautious about drawing a direct line between AI and headcount. Barings is not, he says, planning staffing levels on the assumption that machines will replace people. But AI is already beginning to alter the way its real estate teams work.
“Not necessarily,” he says when asked whether the ability to scale without substantial recruitment is AI-driven. “AI is obviously helping us with a lot of the more repetitive tasks and making us more productive, and over time that could have an impact on people, but that’s not what is driving our headcount plans.”
The experimentation is nevertheless extensive. “We are incorporating AI across the firm,” Duarte says. “We’re testing it, for example, to produce investment committee papers and allocation papers. We’re testing Excel models produced by AI against the models that our analysts are producing. We have AI agents looking at tenant covenants. A lot of it is at test stage at this moment, to be honest, but there are definitely ways that AI is making us more productive.”
Duarte’s own route into real estate was rather less strategic. Born in Portugal, he volunteered for the navy at 18 and remained for three years. “I joined when I was 18 and I did three years,” he says. “It was a great time, a great experience and a great base for me to start my professional life, but I realised it wasn’t what I wanted to do for the rest of my career.”
So, at 21 he left Portugal for Bristol, where he had friends studying, and enrolled at the University of the West of England. “I had friends there and thought, ‘why not give it a try?’. I loved Bristol. I still love Bristol. If I had to live anywhere else in the UK outside London, it would probably be Bristol.”
His entry into property was equally serendipitous. After university Duarte returned to Lisbon and joined the trading arm of a Spanish bank. He had imagined trading would be exciting. The reality disappointed. “It wasn’t for me,” he says. “It wasn’t as exciting as I thought it was going to be.”
Then a friend heard about a job for somebody who could speak Portuguese, Spanish, French and English “He said, ‘I think I’ve got the right job for you.’ And I said, ‘What is it?’ He said, ‘It’s in real estate.’”
The employer was IPD, the property investment data and benchmarking business later acquired by MSCI. Duarte knew little about property, but the languages fitted. “I went to have a look and I loved it,” he says. “It was the best decision I’ve made.”
He moved to London in November 2002 and has worked in real estate ever since, subsequently building experience across 14 European markets and holding roles at multiple companies. There are obvious differences between his two most recent employers. Hines has a substantially larger European organisation. But Duarte says the cultures were more similar than outsiders might assume.
“They are both very collaborative,” he says. “There are a lot of talented people in both organisations and they’re both very much operator-led, vertically integrated real estate businesses. Culturally, they’re actually pretty similar.”
Now, having returned to Barings, Duarte suggests his second spell could be the last major move of his career.
“Coming back to Barings was a big decision to me, and I see myself staying here until the end of my career,” he says. “I think it’ll be a really interesting next 10 or 15 years in terms of what we’re able to do here at Barings with the team that we have.”
Although his professional remit spans Europe, Duarte lives with his wife and children in Lisbon. He commutes weekly to London or wherever else work requires him to be.
The day before our interview he was in Dublin. When we speak, he is in Paris. “I have the longest commute in Barings for sure in Europe,” he says.
The relentless travel makes his priorities when he does get home understandable. “I spend a lot of time with my family,” he says. “I travel quite a lot, so when I’m not travelling I want to spend as much time as possible with my wife and kids,” he says. “Although we travel quite a lot for leisure as well. The kids love travelling.”
There is rugby too. Duarte played until injuries finally forced him to stop. “I love rugby. I can’t play anymore because of injuries. I think I played until too late,” he says. “But I love watching it. I’m quite happy to spend the whole day watching rugby, to my wife’s displeasure.”
His other great interest is wine. Together with friends, Duarte makes a small quantity from a vineyard around an hour north of Lisbon. He is quick to dispel any suspicion that an investment manager might have turned his hobby into another asset class. “This is not a financial venture,” he says.
“It’s a very small number of bottles of wine that we sell to our friends and family generally. We do it more for the joy that we get from the harvest. We have a big party with all of our friends and everyone gets involved. It’s something that we really enjoy doing.”
Inevitably, however, wine and property have found a way of colliding. A Barings colleague in Australia knows about Duarte’s enthusiasm and has arranged investor dinners in Melbourne and Sydney around his forthcoming visit. The concept is to compare wine vintages with real estate vintages.
“I’ve got 10 or 12 wines from around the world and we’re going to compare the different vintages with different vintages of real estate,” Duarte says. “My role is going to be talking about wines as well as talking about real estate in Europe, which should be quite interesting.”
Duarte has returned to Barings convinced that investors are at the beginning of a new European real estate vintage.
The ingredients are not universally appealing: economic weakness in some markets, geopolitical uncertainty, constrained development and still-limited liquidity.
But those difficulties have also produced repricing, scarcity and the chance to acquire assets below replacement cost.
And Barings does not need everything to recover simultaneously. It can back Spain because it is growing and look at Germany because it is struggling; favour residential while remaining open to the best offices; and gain exposure to new development without necessarily assuming all of the development risk.
Duarte left the firm once because he was impatient for a new challenge. Five years later, back at Barings and looking at the opportunities emerging from a long correction, patience may be precisely what the next stage requires.
For someone who makes his own wine, perhaps that should come naturally.
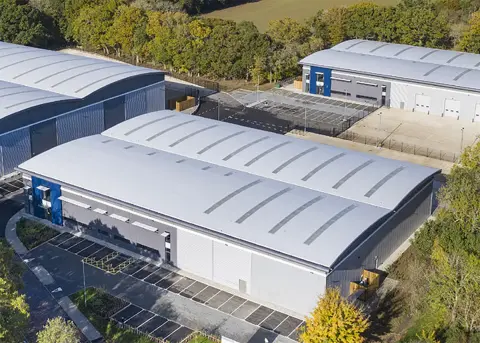
Sheds | £145m bet on the South East
Barings demonstrated its appetite for urban logistics in June 2025 when it paid Blackstone £145.2m for the Access portfolio, comprising four multi-let estates across the South East of England.
The acquisition, made for a core European real estate strategy, included Tyson Park in Basingstoke, The Sterling Centre in Bracknell, Centrapark in Welwyn Garden City and Stratus Business Park in Milton Keynes. Together, the estates contain 28 units totalling 746,795 sq ft and were more than 90% occupied at acquisition.
All four are within an hour’s drive of London, where restricted land availability and high property costs have pushed some occupier demand into surrounding markets.
Barings sees constrained development as supportive of rental growth in the mid-box and multi-let industrial market. The deal therefore encapsulates several elements of the strategy Duarte describes: existing assets in supply-constrained locations, the potential for rental growth and exposure to a logistics segment where occupier demand remains strong.
At the time of the acquisition, Barings said it hoped to follow the purchase with further national and European logistics portfolios and major individual assets across its target markets.
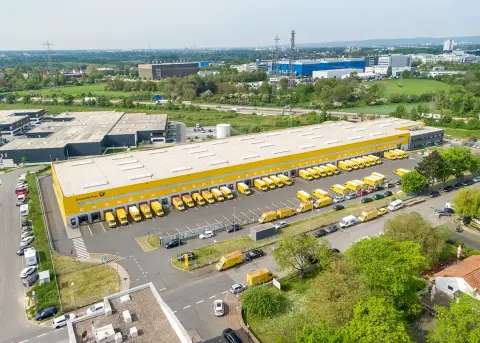
Germany | back into logistics
Barings put its renewed German conviction into practice in early 2026 with the acquisition of three cross-dock logistics properties from Dietz AG in the Frankfurt/Rhine-Main region for a European core real estate strategy.
The three modern assets provide 17,975 sq m of space and were fully occupied by a single tenant at the time of acquisition, offering existing income alongside the potential for rental growth over the medium to long term.
Location is central to the investment case. The Frankfurt/Rhine-Main region sits at the heart of Germany’s transport network, with access to the Frankfurt motorway interchange and Frankfurt Airport, one of Europe’s major air-freight hubs. The wider metropolitan region also generates substantial logistics demand from retailers and industries including chemicals and pharmaceuticals.
Barings described the purchase as evidence of its continuing conviction in German logistics, where it is seeking opportunities across core, core-plus and value-add strategies.
For Duarte, Germany’s economic problems have contributed to the repricing that is making the country interesting again. The transaction demonstrates Barings’ willingness to deploy capital where strong property fundamentals can be found amid a much more difficult macroeconomic picture.
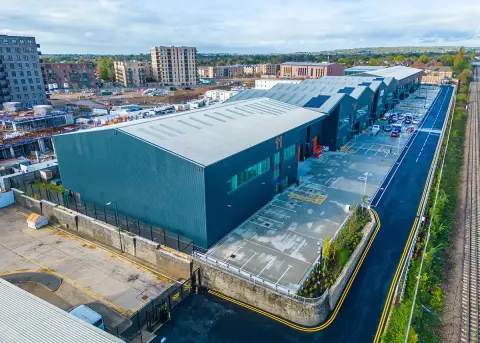
Urban industrial | £38.5m Harrow acquisition
Barings added to its UK urban industrial holdings in July 2026 with the £38.5m acquisition of Eastman Edge in Harrow from Big Yellow Group.
The newly built multi-let light-industrial estate, acquired for a European core real estate strategy, sits 11 miles from central London and has access to the A40, M1 and M25 as well as public transport and Heathrow Airport.
The estate provides flexible modern accommodation for uses including last-mile distribution, services and local trade. It also has EPC A ratings, electric-vehicle charging and solar photovoltaic panels.
For Barings, the appeal is the combination of a densely populated urban market, restricted land supply and demand for modern industrial space close to customers – essentially the demographic, location and supply characteristics Duarte says sit at the heart of its investment decisions.
The purchase followed the much larger £145.2m Access portfolio transaction in 2025 and reinforces Barings’ appetite for multi-let and urban industrial property in the UK.
Barings says its wider pan-European strategy continues to target urban industrial, logistics and living opportunities across risk profiles ranging from core to value-add.
Subscribe now and stay informed
Joining the CRE Media Europe mailing list is quick and simple. Just provide your contact details below to be added to our distribution list and start receiving the latest news, magazines and special updates, all free of charge.
Commercial real estate (CRE) Media Europe is a free to access news and information service providing dependable, independent journalism. Our mission is to provide the pan-European real estate market with the latest trends and data points, and provide key analytical coverage to help you make better decisions in your business.
To discuss advertising and commercial partnership opportunities please contact eddie@cremediaeurope.com