Colliers: German office market enters 'new normal'
Germany’s commercial real estate market has entered a new cycle defined by realistic asset pricing, selective capital deployment, and a pivot away from mega-deals, according to Michael Baumann, head of Capital Markets Germany at Colliers Germany.
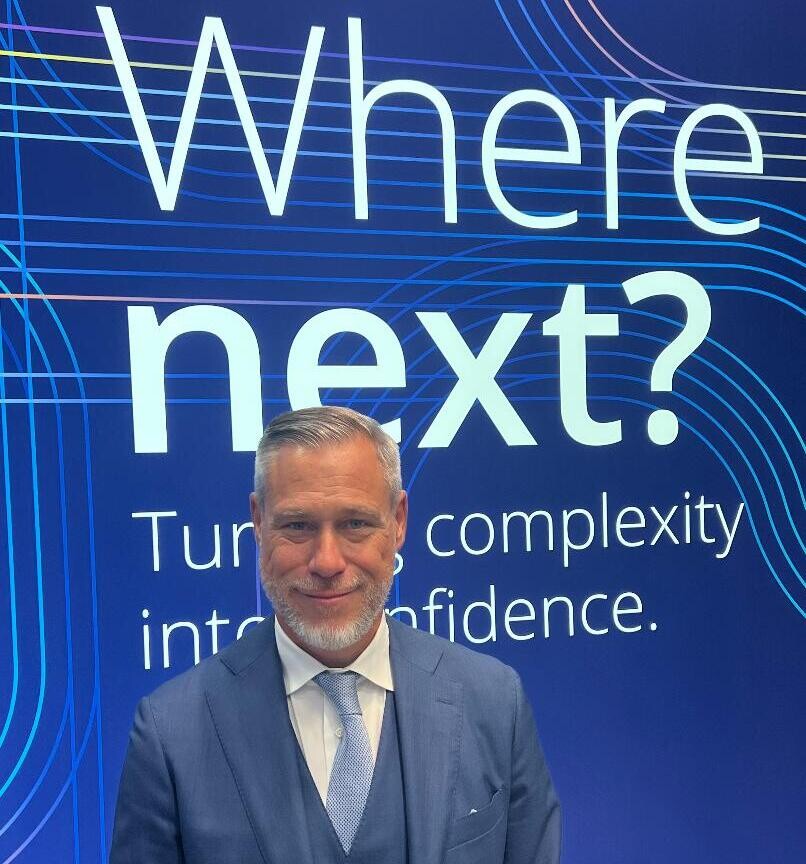
Michael Baumann
Speaking to CRE Media Europe at EXPO REAL, Baumann highlighted that while institutional mega-transactions remain constrained, market liquidity has recalibrated around core, core-plus, and value-add properties priced between €10 mln and €60 mln. This activity spans both Germany’s Top 7 metropolitan areas and key regional hubs.
Elevated interest rates and broader macroeconomic friction have reshaped investor expectations, but adjusted risk-return profiles are bringing capital back into the office segment.
"The risk-return profile is reaching a point where investing in German offices makes economic sense again," Baumann noted. "Office performance has become highly differentiated. Prime assets in strong locations across the Top 7 and Top 15 cities continue to perform well."
Market pricing has adjusted significantly to reflect current risk dynamics. Colliers recently closed the transaction of a single-tenant office asset in a secondary Munich location at a 12% yield.
Capital remains selective
While overall market liquidity is constrained compared to peak historical volumes, specific buyer groups remain active, including domestic family offices, select German institutional buyers and French SCPIs.
Despite wider market headwinds, Germany maintains strong relative transaction volume compared to European peers. Total commercial real estate volume in Germany reached approximately €15 bn across the first three quarters of the year—comprising over 160 individual office deals—providing a functional baseline for the market.
Future supply constraints
Looking toward 2027, Baumann foresees increased activity driven by value-add and core-plus investors as the spread between seller expectations and formal fund valuations closes.
At the same time, severe development shortfalls over the past three to four years—caused by elevated land costs and restrictive debt financing—are creating a medium-term supply bottleneck. As legacy development pipelines wrap up with minimal new construction starts to replace them, existing prime stock will face tightening availability, applying sustained upward pressure on office rents across major urban centres.
Branislav Pekic
Subscribe now and stay informed
Joining the CRE Media Europe mailing list is quick and simple. Just provide your contact details below to be added to our distribution list and start receiving the latest news, magazines and special updates, all free of charge.
Commercial real estate (CRE) Media Europe is a free to access news and information service providing dependable, independent journalism. Our mission is to provide the pan-European real estate market with the latest trends and data points, and provide key analytical coverage to help you make better decisions in your business.
To discuss advertising and commercial partnership opportunities please contact eddie@cremediaeurope.com