Cross‑border investment into European offices rises, Savills analysis
Cross‑border investment into European offices has increased to 39% so far in 2026, up from 36% in 2025, according to Savills’ latest analysis of RCA data.
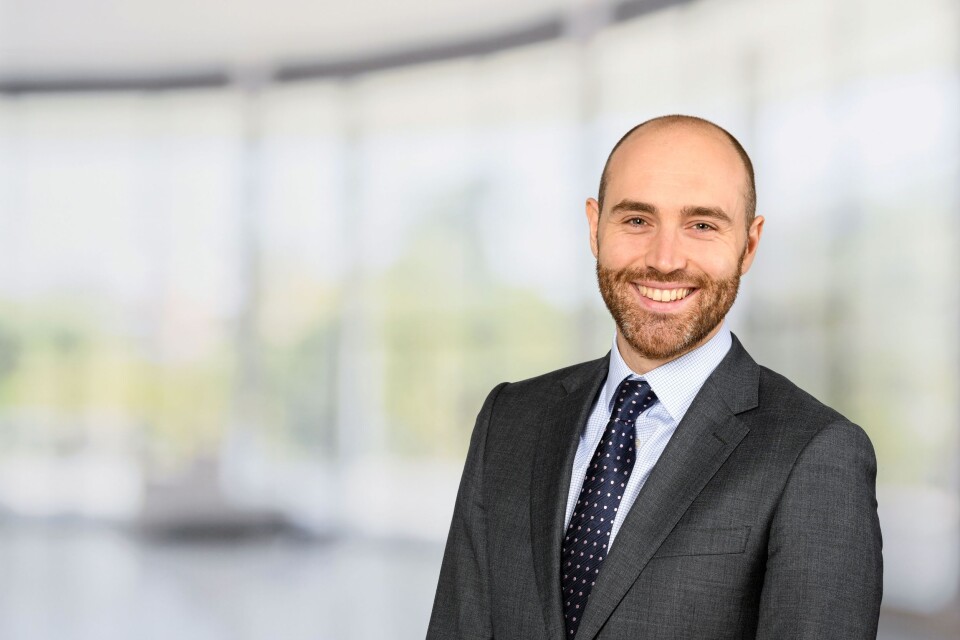
James Burke, Savills
The rise reflects continued activity from several pockets of capital across Europe, even as overall investment volumes remain subdued.
Savills notes that demand is being supported by a diverse group of active buyers. In Sweden, Alecta recently acquired a €451 million Stockholm office portfolio, while French SCPIs continue to expand across multiple geographies, targeting offices as part of broader mixed‑asset strategies. Several SCPIs are now assessing potential entry into Scandinavian markets. Within Central and Eastern Europe, Czech and Hungarian investors remain acquisitive both domestically and increasingly across Western Europe. Private investors also remain active, including Pontegadea’s recent acquisition of Capital 8 in Paris, while core German insurance and pension capital is selectively bidding on prime product.
After a period of stability, higher long‑term borrowing costs prompted outward yield movement across several European cities in Q3 2026. Savills reports that average prime office yields rose by 13 bps to 5.1%. Warsaw, Paris CBD, Brussels, London City, the West End and Manchester all moved out by 25 bps, while Germany’s top six cities shifted between 10 and 20 bps. Lyon saw a 50 bps outward move to 6.00%, and Lisbon moved out 40 bps to 5.00%. In contrast, Stockholm moved in by 15 bps to 3.75%, reflecting strong domestic demand for prime assets.
James Burke, Director, global cross border investment at Savills, said occupational markets delivering rental growth will help maintain the appeal of European offices. “The supply squeeze and tenants’ flight to quality present repositioning opportunities in or close to CBD locations while new development remains broadly unviable. Office‑based employment growth in key knowledge hubs across the professional, tech and finance sectors is expected to underpin new tenant demand.”
Mike Barnes, European office research director at Savills, added that investor sentiment has begun to improve. “INREV’s latest sentiment survey shows that investor sentiment picked up in the third quarter following the initial US/Iran conflict, although it remains below the 50‑mark separating expansion and contraction. Sentiment towards the office sector improved by 15 percentage points over the last three months, supported by solid occupational dynamics and rental growth prospects.”
Subscribe now and stay informed
Joining the CRE Media Europe mailing list is quick and simple. Just provide your contact details below to be added to our distribution list and start receiving the latest news, magazines and special updates, all free of charge.
Commercial real estate (CRE) Media Europe is a free to access news and information service providing dependable, independent journalism. Our mission is to provide the pan-European real estate market with the latest trends and data points, and provide key analytical coverage to help you make better decisions in your business.
To discuss advertising and commercial partnership opportunities please contact eddie@cremediaeurope.com